Country Risk Radar 2026 for Export CFOs
This video outlines a country-risk framework for export CFOs that combines economic indicators with local payment practices. It covers regional collection strategies, weekly receivables controls, and a 90-day implementation plan for more disciplined credit management.
Key takeaways
- Adjust credit limits as exchange rates, local liquidity conditions, and insolvency patterns change.
- Match recovery tactics to the market: regulatory enforcement in the EU/UK, senior-level negotiation in MENA/APAC, and shorter credit cycles with day-31 third-party involvement in LATAM and emerging markets.
- Classify 95% of invoice disputes and assign technical responsibility within two business days; investigate five-day payment deviations among the highest-exposure accounts.
- Aim for a Collection Efficiency Index of at least 85%; a reading below 75% signals weaknesses in credit screening or recovery before litigation.
- Sequence implementation across country-level diagnostics, standardized escalation and dispute evidence, then ERP risk-feed integration and executive reviews.
What this video covers
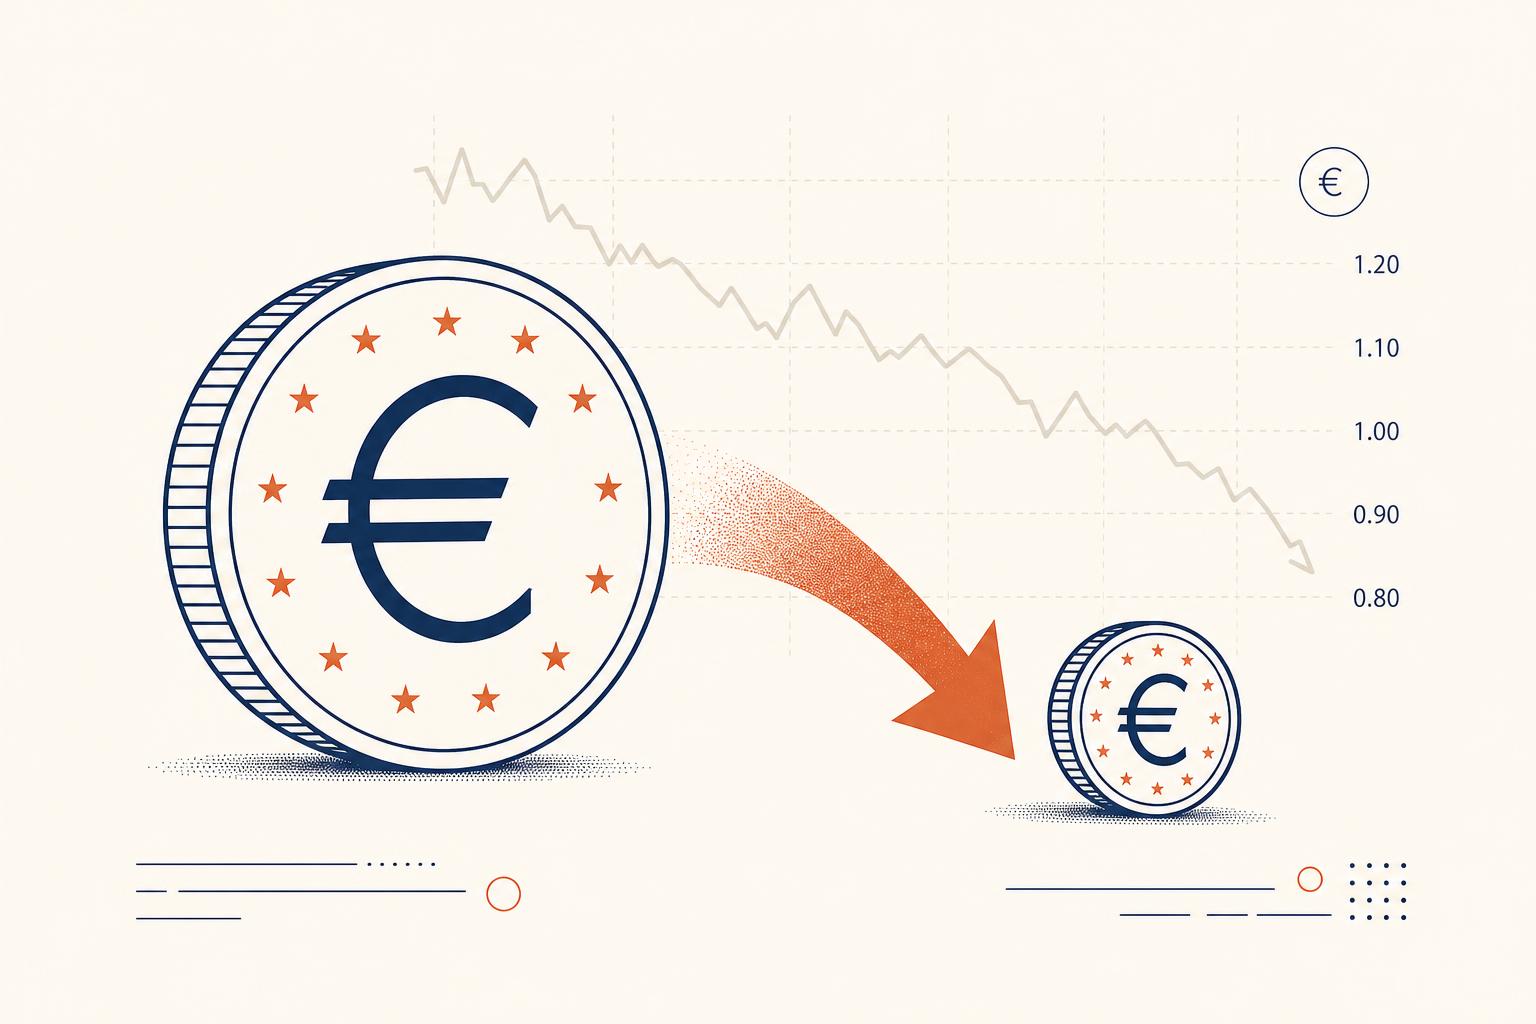
The video explains why export CFOs need to anticipate country risk rather than wait for overdue balances to accumulate. It connects macroeconomic conditions with local payment behavior, showing how high borrowing costs can encourage buyers to use unpaid invoices as inexpensive financing. Credit decisions therefore need to reflect exchange-rate movements, geographic liquidity, and insolvency developments. Regional execution is central to the framework. In EU and UK markets, the emphasis is on late-payment rules and statutory interest. For MENA and APAC, the approach favors senior-level mediation and culturally sensitive negotiation before escalation. In LATAM and emerging markets, it recommends tighter credit cycles and third-party action on day 31 to limit exposure to currency depreciation. The video also sets out weekly oversight measures: prompt dispute classification and ownership, monitoring payment changes among major accounts, and tracking the Collection Efficiency Index against an 85% target. Finally, it presents a three-stage, 90-day rollout. The first month examines overdue balances by country, identifies buyers who ignore automated notices, and maps legal support. The second establishes consistent escalation steps and dispute documentation. The final month introduces live country-risk data into the ERP and monthly leadership reviews that use actual recovery times to reassess credit appetite.