Most small businesses discover cash problems the same way they discover a flat tire — by hearing the rim scrape asphalt. A 13-week rolling cash flow forecast changes that dynamic entirely, giving you a 6-to-8-week window to spot shortfalls while solutions are still inexpensive and dignified. It is, without exaggeration, the single most useful spreadsheet your business will ever maintain.
You already know the panic. You've stared at a bank balance on a Thursday afternoon and done mental arithmetic about whether Friday's payroll will clear. You deserve better than that, and so does your team. This article walks you through why the 13-week model works, how to build one in under an hour, and why the businesses that use it consistently outperform the ones running on optimism and vibes.
Why Do Most SMBs Fail at Cash Flow Forecasting?
Percentage of business failures attributed to poor cash flow management and visibility.
Standard P&L statements are often 3-4 weeks old by delivery, rendering them useless for real-time crisis prevention.
Distinguishing between "earned revenue" and "banked cash" is the most common hurdle for growth-stage finance teams.
What Exactly Is a 13-Week Cash Flow Forecast?
A rotating 90-day window that provides a granular, weekly look at every anticipated dollar movement.
- Customer Payments
- Tax Refunds
- Asset Sales
- Fixed Payroll
- Vendor Obligations
- Debt Service
How Far Ahead Can a 13-Week Forecast Actually Predict Problems?
Reduction in emergency borrowing for firms utilizing a rolling 13-week cash visibility model.
The operational window where data remains concrete enough to trust and far enough out to pivot strategy.
Planned credit facilities at 6% vs. emergency merchant cash advances that can exceed 18% in effective interest.
What Are the Most Common Cash Flow Forecasting Mistakes?
Your forecast should not include the $47,000 invoice you sent to that client who has paid late every single quarter for two years. It should include a realistic estimate of when that $47,000 will actually hit your account — which, based on pattern recognition, is approximately six weeks after the due date, minus whatever your AR team manages to shake loose with polite follow-ups.
Ignoring seasonality. If your business slows in Q1, your forecast should reflect Q1 reality, not your annual average. Spreading revenue evenly across 52 weeks is not forecasting. It is creative writing.
Setting it and forgetting it. A forecast you built in January and never updated is a historical document, not a planning tool. The rolling part of "rolling forecast" is not optional. Update weekly, compare actuals to projections, adjust. Twenty minutes per week — roughly the time you currently spend refreshing your banking app and hoping the numbers change.
How Does Accounts Receivable Factor Into Cash Forecasting?
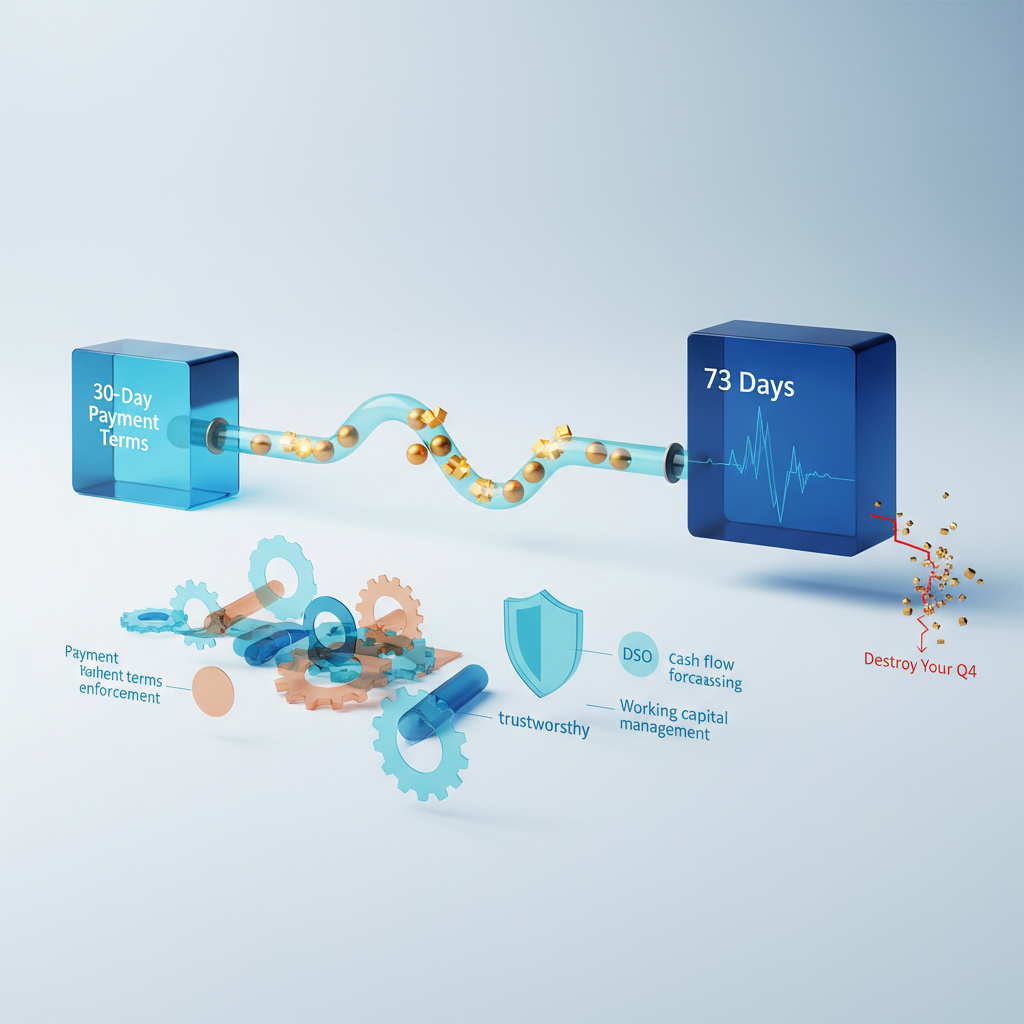
The variance between stated net-terms and actual payment behavior is where liquidity crises begin.
Forecast based on historical behavior (e.g., Client A typically pays Net-52) rather than the Net-30 printed on the invoice.
Every single day shaved off your Days Sales Outstanding (DSO) adds 24 hours of cash-on-hand to your operating runway.
Can a Small Business Build This Without Expensive Software?
Yes. A spreadsheet works. Seriously. The 13-week forecast predates every SaaS tool currently marketing itself as essential, and it will outlast most of them. Google Sheets, Excel, even a well-organized notebook — the tool matters far less than the discipline of updating it weekly.
That said, the value of the forecast scales with the accuracy of your inputs. If your AR data is scattered across email threads, sticky notes, and that one spreadsheet Kevin started in 2019, your forecast will inherit all of that chaos. Clean AR data in, clean forecast out. Garbage in, Wednesday-afternoon panic out.
The 13-Week Forecast Is a Flashlight, Not a Crystal Ball
Forecasting does not prevent cash problems. It reveals them early enough that you can respond like a strategist rather than react like someone whose hair is on fire. The businesses that survive unpredictable markets are not the ones with the best luck — they are the ones who saw the gap at Week 8 instead of Week 0.
The first step is knowing what is coming. The second step is making sure the money you are already owed actually arrives. Uncollected receivables are the silent killer of otherwise healthy forecasts — they turn your projection from a plan into a fiction.
Know what's coming. Get a free AR audit — cllcty.com →
Sources
- Treasury & Risk Management. (2024). "Cash Forecasting Practices in Mid-Market Companies." Treasury & Risk Annual Survey Report.
- Federal Reserve Banks. (2024). "Small Business Credit Survey." Federal Reserve System. https://www.fedsmallbusiness.org
- PYMNTS.com. (2024). "B2B Payments and Cash Flow Management Report." PYMNTS Intelligence.
- Association for Financial Professionals. (2024). "AFP Liquidity Survey: Cash Flow Forecasting Benchmarks." AFP Research.
- Intuit QuickBooks. (2024). "Cash Flow and Small Business Survival: Annual Report." QuickBooks Research & Insights.
Sarah Lindberg
International Operations Lead
Sarah coordinates our global partner network across 160+ countries, ensuring seamless cross-border debt recovery.